New here? Watch the 2-minute walkthrough
New video every week on NYPD, FDNY and 9/11 family money questions. Subscribe on YouTube
What counts, and what does not
Not your base pay alone. Overtime, night differential and worked vacation count. Leave out uniform allowance and FLSA pay, which don't count toward the pension (Tier 2 booklet p.17).
Counts: base salary, overtime, night differential, holiday pay, worked vacation, portal to portal and allowable longevity.
Does not count: uniform allowance, Fair Labor Standards Act payments, and excluded longevity.
Longevity is not automatically pensionable. At 20 years of service the 5 and 10 year longevity payments become pensionable. At 25 years the 15 and 20 year payments become pensionable too. So crossing those marks changes what your salary base is figured on, separately from any raise.
If the final 12 months ends up being the figure the Fund uses, that becomes a timing question. A date set soon after your 25 year mark measures a window built mostly on the narrower longevity basket, because full longevity only became pensionable when you crossed 25. The booklet does not settle whether that step applies to pay earned after the mark or attaches once you have 25 years, and the difference can sit in your pension for life. Ask the Fund before you set a date. This is separate from the rank based Pension Longevity Enhancements at 25, 30 and 35 years, which are a percentage tied to rank rather than a question of what enters your salary base.
Which years get averaged depends on your tier. Tier 3 uses your highest 3 consecutive years. Tier 2 uses the greater of the final 12 months, the final 36 months, or the best 3 consecutive calendar years. Since September 28, 2026 (Chapter 312 of the Laws of 2026) that includes members appointed on or after July 1, 2000 who retire on or after that date. Before the law they were paid on the final 12 months only.
A cap applies either way. On a final 12 months basis, pensionable earnings cannot exceed 120% of the previous 12 months. On a 36 month or best 3 basis, no single year can exceed 120% of the average of the two years before it.
One thing worth flagging. The Tier 2 booklet lists these seven components on page 11 and a shorter set of five on page 16, leaving out holiday pay and portal to portal. We show the longer list.
Sources: NYC Police Pension Fund Tier 2 Summary Plan Description (June 2026) pages 11, 16 and 17; Tier 3 Summary Plan Description (June 2026) pages 7 and 10. Confirm your own service credit and earnings with the Fund. Their figure is the one that counts.
Your pension a month shows here, free, once the boxes above are filled in.
Your age turns this into your Pension Printout, with the five decisions that go with it.
Make it more exact (optional)Your best 3 years may raise this. Add them.
Want your numbers in a personal guide and video?
Eslyn Hernandez reads what you entered and emails you a personal pension guide and a short video within one business day. No cost.
What moves your numberWhat your number means, and the inputs that move it most
Each line changes one input and holds the rest. Real decisions move several at once, which is what a planning conversation is for.
Why your number is what it is
The calculator gives you a number. This section is about the decisions inside it: what builds it, which inputs move it most, and how to keep it. It updates live as you change the inputs above, and it is a hypothetical illustration built only on the figures you entered, not a projection and not advice.
Years of service and salary still start as an example. Your tier comes from the date you entered. Change the years and salary above and these sentences describe you.
Your numbers ride inside the link, and the link is not sent to us. Anyone you send the link to will see the numbers you entered.
These sentences and figures are hypothetical illustrations based only on the numbers entered above. They are one of several possible outcomes, not a prediction. You can change the inputs at any time to see how the picture shifts.
This is educational information, not investment, tax, or legal advice, not a recommendation to retire, keep working, roll over, or convert, and not a guarantee. Sirmium Capital LLC is a New York state-registered investment adviser and is not registered with the SEC. Using this tool does not create an advisory relationship. Confirm your figures with the NYC Police Pension Fund and, for tax questions, a qualified tax professional.
A 2026 law changed how some Tier 2 pensions are figuredWhat it changes, and who it reaches
A 2026 law changed how some Tier 2 pensions are figured
S7808A was signed on September 28, 2026 (Chapter 312 of the Laws of 2026). If you were appointed from July 1, 2000 to June 30, 2009 and retire on or after that date, your salary base is now figured the same way as for members appointed before July 1, 2000: the greater of your final 12 months and your best 3 consecutive years. Give your appointment month and your best 3 consecutive years in Step 1 and the figure above uses it.
You will get the free NYPD checklist right away. After that we only write when the bill moves. Unsubscribe anytime. When you send your email, the figures you typed are saved with it, so we can prepare for a call. They're never put in an automated email.
Ask for your pension guide by email: the same email carries this alert.
I do not have the date to hand
You can pick a tier and still get a number. It will be a worked example rather than yours, and your Pension Printout still needs the date before it will print anything.
Your age turns this into your Pension Printout
Make it more exact (optional)
None of these is needed to get your printout.
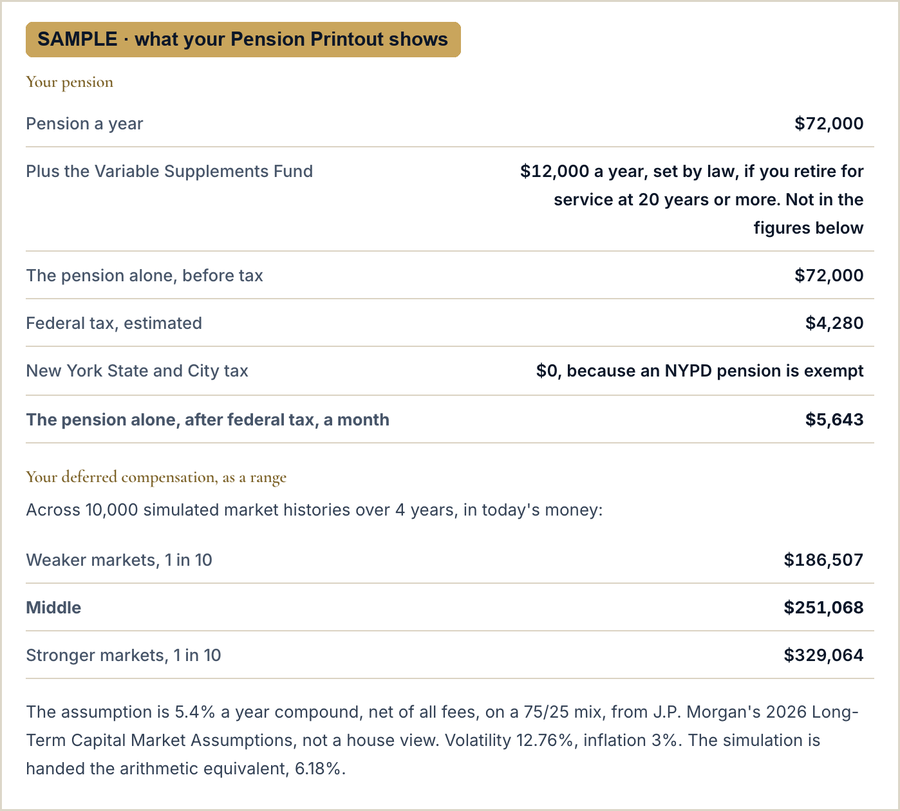
This is what you get: your pension a year and a month, the tax on it, the $12,000 VSF where it applies, and your 457(b) as a range.
Rather talk it through? Free 15-Minute Call with Eslyn Hernandez, nothing to sign.
Turn your pension into a retirement plan
Skip this, go to Step 5. Your printout doesn't need it.
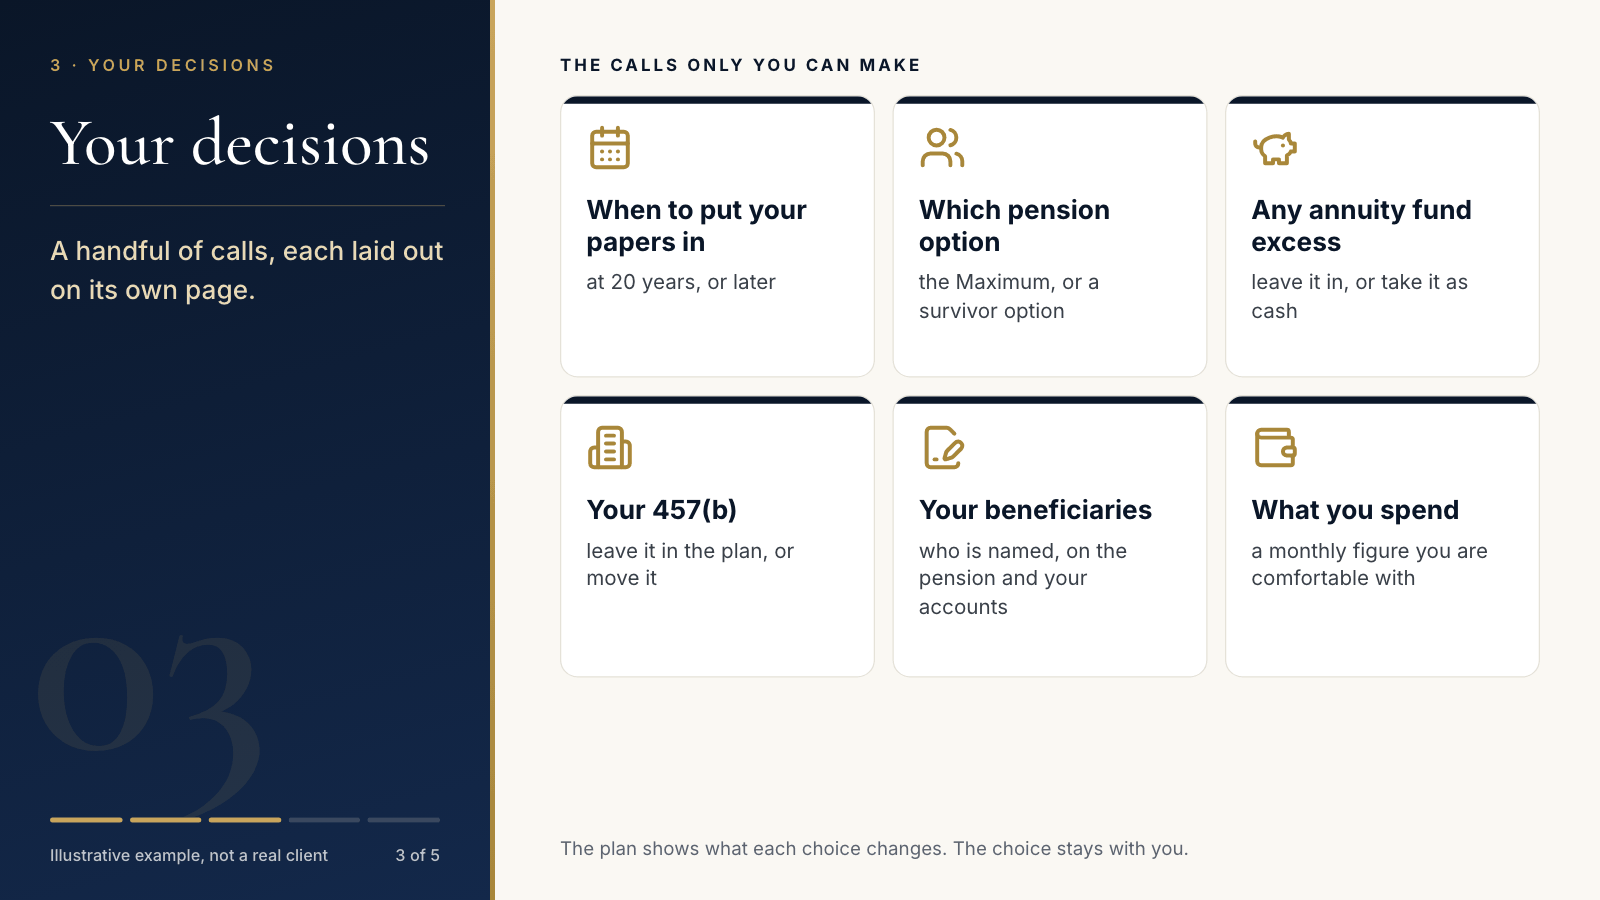
Your Pension Printout shows what the pension pays. This part plans the life around it: when you go, what you'll live on, your 457(b), your family, and the work you'll do after the job. Retiring after 20 years often means retiring in your 40s, so if you'll take another job, security or anything else, put its pay in number 5. Each answer is written into your printout.
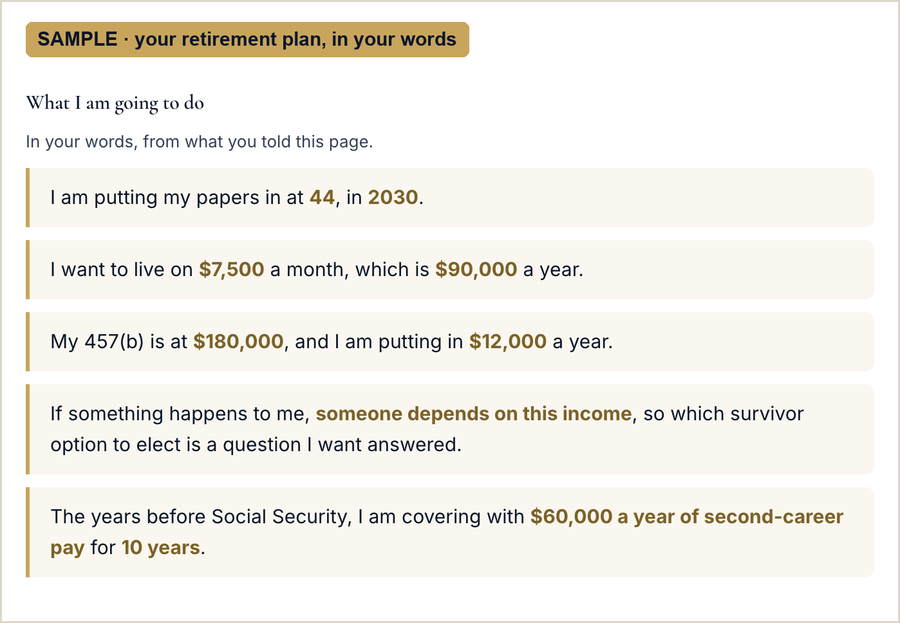
Five decisions. You make them, we do the arithmetic.
What you do here: finish five short sentences about your own retirement. Once the boxes above are filled in, the first one fills itself in.
What you get: each sentence written into your Pension Printout with the numbers worked out underneath, and anything you can't settle listed as a question for the free 15-minute call.
Nothing here is a recommendation. These are your calls, in your words.
-
I am putting my papers in at …
Filled in from your start month, years of service and age above. Change it if that's not right. -
I want to live on … a month
$What leaves your account in a normal month. Not a budget you intend to keep to. -
My 457(b) is at …
$$ -
If something happens to me, …
Which survivor option to elect is not decided here. The options and what each one does to the cheque are set out on the survivor options page, and the election itself is a conversation, not a calculator output. -
The years before Social Security, I am covering with …
$$$A public benefit corporation means the MTA, Health + Hospitals, the Port Authority and the like. "State, City or school" covers New York State, the City of New York and a school district. It matters because a New York public pay cheque and a private one land differently against your pension under Section 212.
Your pension is one piece. This is what it looks like next to the rest.
The calculator above gives you the pension. Retirement is that plus everything else, arriving in the same years. Below is the same income laid out year by year from the day you leave, so you can see where each piece switches on, where one stops covering another, and where the gaps sit. It is a hypothetical illustration built on the figures you entered, not a projection and not advice.
See the year by year table
Gross figures before tax, in today's dollars, and rounded. This view does not model investment growth on the 457(b), Social Security, the Tier 3 age-62 reduction as a dollar amount, or the Police Officer and Captain longevity enhancements. The Detective, Sergeant and Lieutenant step is in the pension when you give your rank and years in rank. It is an illustration for discussion, not a plan. What you do with your own numbers is a conversation for a licensed adviser, and William Harrison, our Co-Founder and CIO, leads that work.
Your pension is one number. A plan also covers these five.
A Financial Plan puts your own numbers on each one. Whether one is worth it for you is a question for the Free 15-Minute Call.
- Your Annuity Savings Fund (Tier 2): take part of it as a lump sum, or leave it for a larger pension for life.
- Your 457: where it sits after you leave, and the penalty rule that changes if it moves.
- Your union annuity: what happens to it when you retire, and what moving it would cost.
- Your banked VSF: the lump sum for years past 20, and where it can go.
- Your pension option: the maximum, or a survivor option, and who that protects.
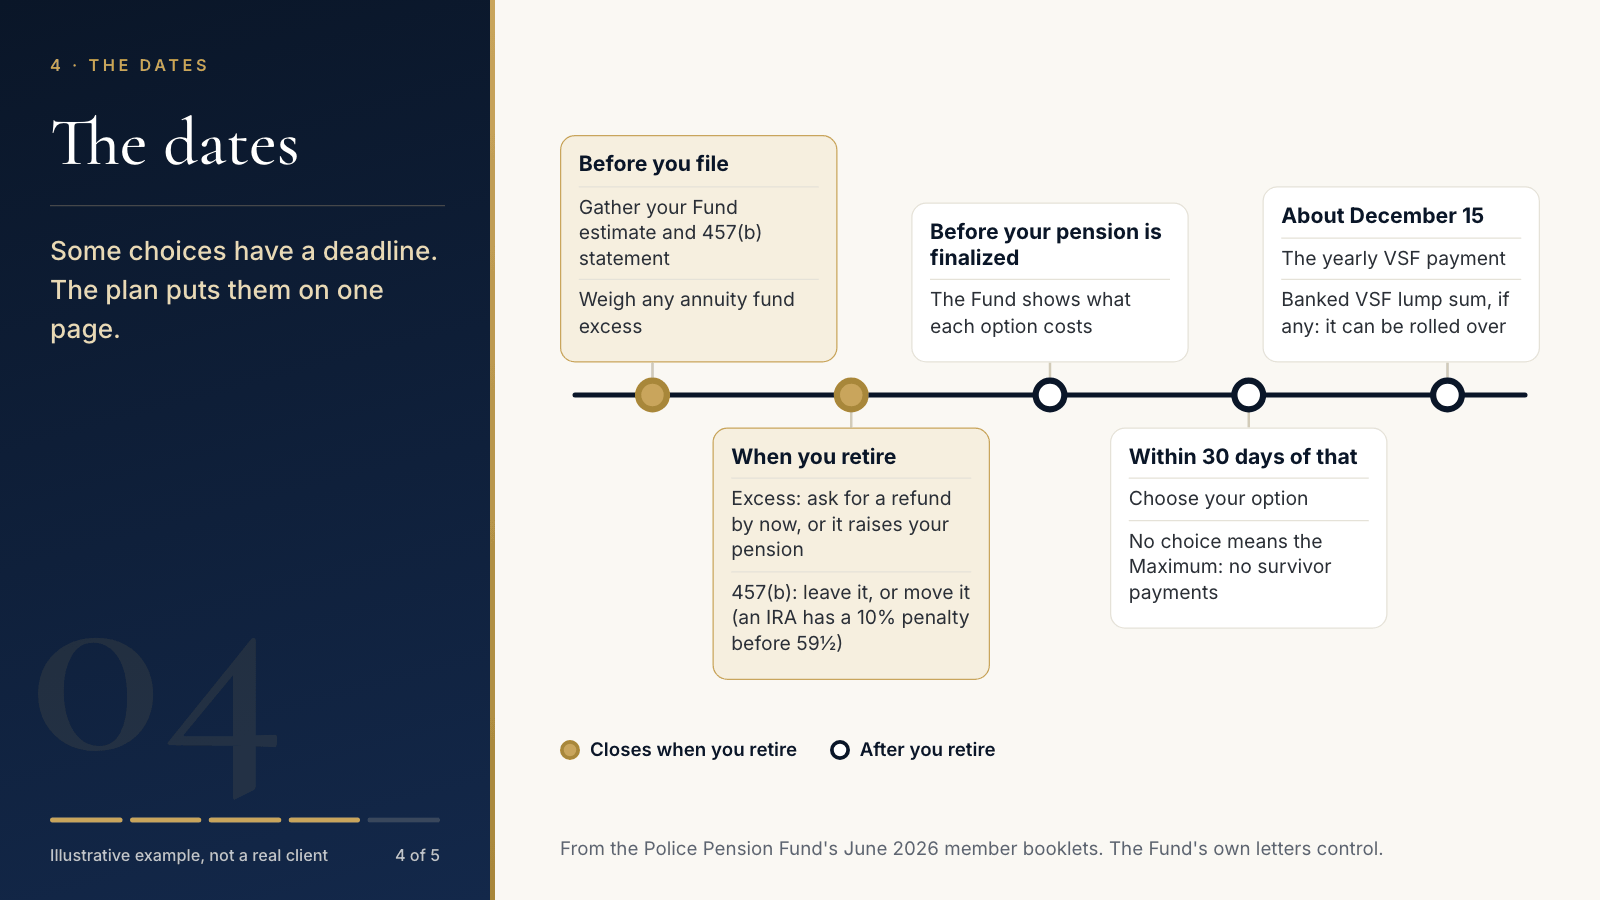
The Fund gives you its official estimate when you sit down with a retirement processor to file. This gives you the picture years before that.
Sources: final withdrawal, Tier 2 booklet pp.12 and 14; banked VSF (the VSF DROP), Tier 2 p.20 and Tier 3 p.20; the retirement processor's estimate, Tier 2 p.16 and Tier 3 p.13; pension options, Tier 2 p.23 and Tier 3 p.20. June 2026 NYC Police Pension Fund booklets.
If you ask for your guide by email, these go with it, so we can prepare.
Your Pension Printout opens here. Then you can ask for a pension guide built on it and pick a time for a Free 15-Minute Call.
What is in it: what the pension pays, how each survivor option works and what to ask the Fund, and, if you gave a balance, what your 457(b) could be worth as a range rather than one number. Your email opens three more sections, including where the gaps sit before Social Security. It is worked out on this device from what you typed.
Want a pension guide built on these numbers?
Eslyn Hernandez reads what you entered and emails you a personal pension guide and a short video within one business day: what your pension pays, the decisions still open, and what each one changes. Your email also opens the three closed sections below. It signs you up for the bill alert too, so you hear the day S7975B moves.
No cost. Eslyn Hernandez reads every request. The figures you typed are saved with your email so we can prepare; they're never put in an automated email. See a sample plan
Your request is in.
Eslyn Hernandez will email your pension guide and a short video from eslyn@sirmiumcapital.com within one business day.
Want to go over it together? Pick 15 minutes below. Nothing to sign.
Calendar not showing? Open it in a new tab.
New video every week on NYPD, FDNY and 9/11 family money questions. Subscribe on YouTube
What the plan meeting looks like
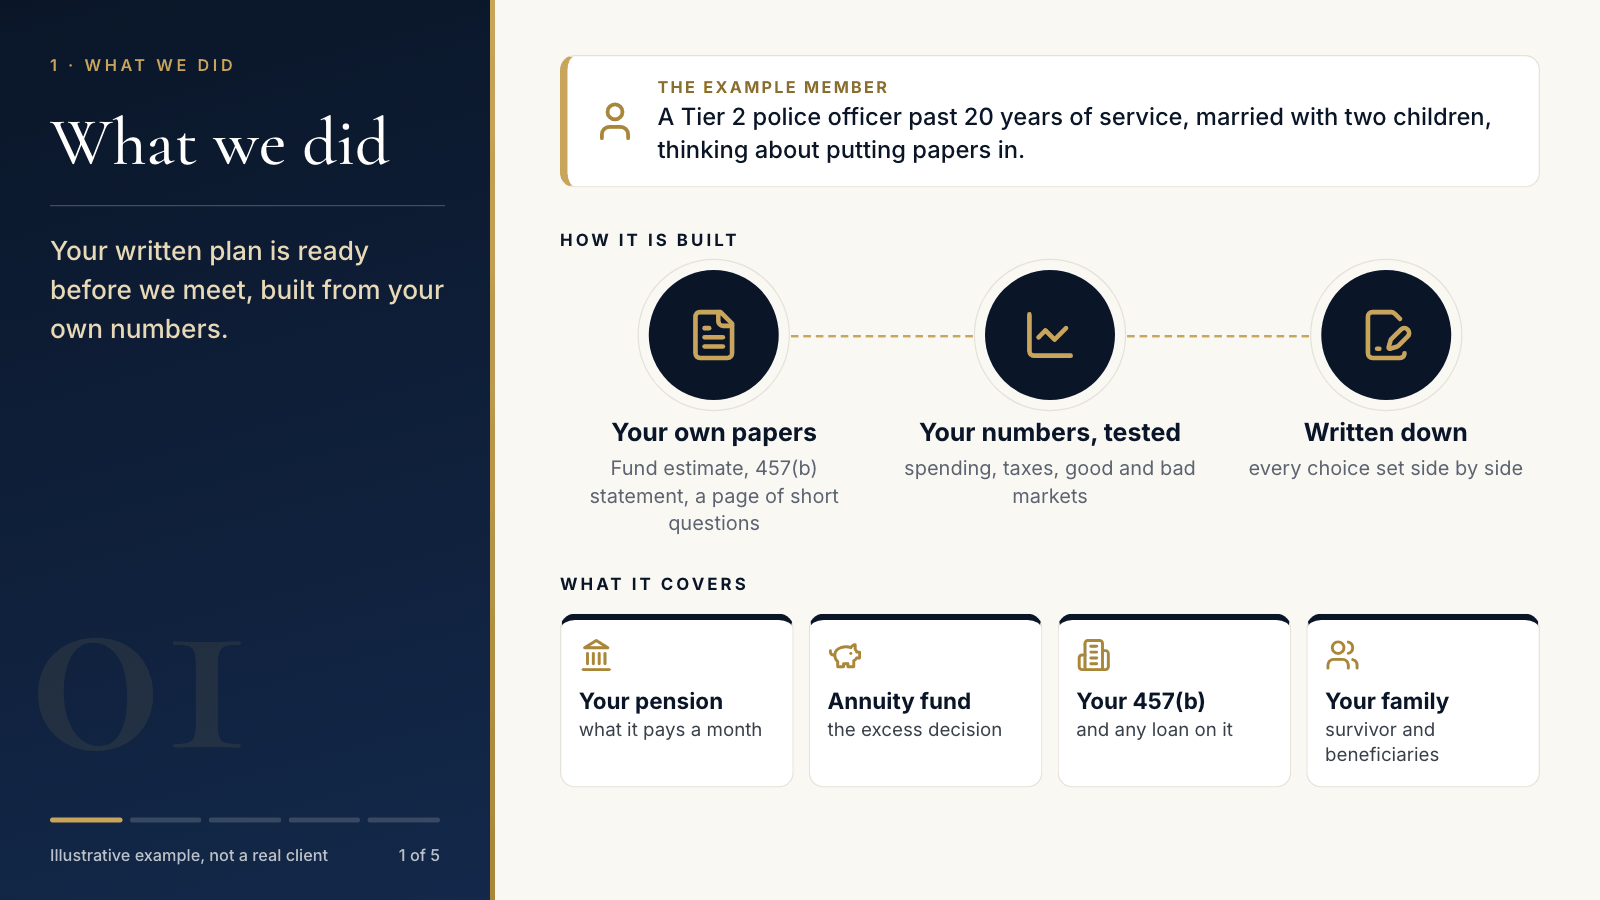
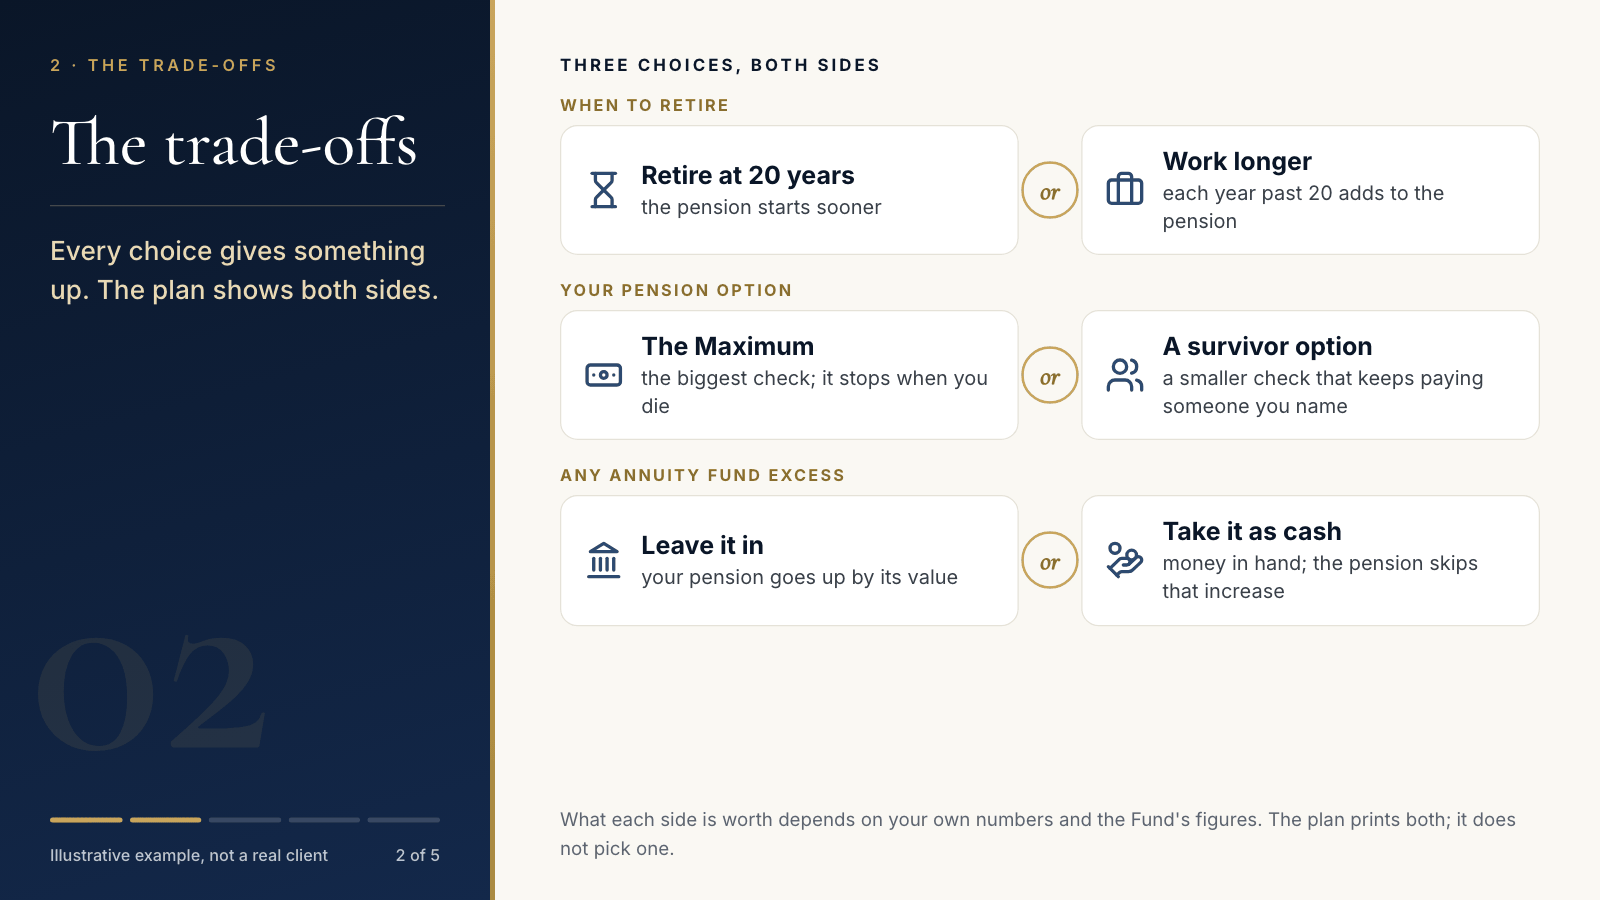
Swipe or scroll for all five slides. An illustrative officer, not a real client.
Next: our free NYPD Retirement Lessons
One short lesson per retirement decision. Two that bear on the figure above:
Your pension, line by lineThe tax lines, the VSF and the Death Gamble
Three answers and the number below is yours. Until you fill them in it shows a worked example on a typical officer, so you can see what the page does before you type anything. Your tier is not guessed here, it comes from the date above.
Your Pension Printout. Your pension a month, the five decisions that go with it, and the questions worth taking to a Free 15-Minute Call.
Every tier change falls on the first of a month, so the window is all the formula needs. Your Pension Printout still needs the exact month before it will print.
—
—
Important: This calculator gives hypothetical illustrations for education only. They are not investment, tax, or legal advice, not a recommendation, and not a guarantee. Your actual result will differ. Sirmium Capital LLC is a New York state-registered investment adviser and is not registered with the SEC.
Tier 3 only: under current law (RSSL § 511) a Tier 3 pension is reduced starting at age 62 by 50% of your primary Social Security benefit, whether or not you have filed for Social Security. This calculator shows the amount before that reduction, so Tier 3 figures for age 62 and later are overstated; a bill to repeal the offset (S7975B) remains in committee and is not law.
How these figures are calculated, and the sources behind them
Pension estimate follows the NYC Police Pension Fund Tier 2 & Tier 3 Summary Plan Descriptions (June 2026) and current law: Tier 2 = 1/40 of final average salary per year to 20 years (50%) plus 1/60 per year thereafter; Tier 3 = a flat 50% of final average salary at 20 years under Chapter 55 of the Laws of 2025 (Part SS), with additional years buying escalation eligibility rather than a higher base percentage.
This estimate does not model the Fund's Police Officer and Captain longevity enhancements (increases at 25 years and above that apply in both tiers), so members in those ranks approaching 25 years may see a figure that is conservative for them. For a Detective, Sergeant or Lieutenant who gives rank and years in rank, it includes the 5%, 10% or 15% step under NYC Administrative Code 14-114(d), figured on the contract's base top pay (1st Grade pay for every Detective); the Fund's own figure can be higher if it counts longevity or an assignment rate. Pay figures are from the City's current police contracts and change when each contract is renewed.
VSF of $12,000/yr is set by law for members of either tier who retire for service with at least 20 years of credited police service (Tier 2 booklet p.19, Tier 3 booklet p.20). Two funds pay it and the split is by rank at retirement: the police officers’ fund under NYC Administrative Code § 13-271, and the superior officers’ fund under § 13-281 for anyone who retires as a sergeant or above, or as a detective (§ 13-278 defines the term, and § 13-268 defines a police officer as someone who was not a superior officer at retirement). The amount is identical. A Tier 3 member who reaches the mandatory retirement age with under 20 years of service does not get it (Tier 3 booklet p.16). That age is 65 since Chapter 311 of 2026; the booklet predates the law and still prints 62.
Confirm specifics with the NYC Police Pension Fund, the NYC Deferred Compensation Plan, and a qualified tax professional before acting.
NY does not tax NYPD pension or VSF income. 457(b) withdrawals are NY-taxable beyond a $20,000 exclusion if you are 59½+. Federal figures use 2026 brackets (IRS Rev. Proc. 2025-32). RMD age, IRMAA thresholds, and tax law can change.